Five Charts that Illustrate the Size and Scope of Consumer Debt

Emy Urban
Manager, Events and Operations
Consumer debt has reached record highs despite an economy more robust than at any point since the end of the Great Recession. Unemployment is at a historic low and wages are up, leading to many rosy interpretations of current debt trends. Yet signs continue to point to the fragility of many families’ finances, and households’ experiences with debt in the current economy vary widely along demographic and geographic lines. Learn how in these five charts from the Aspen Institute’s Expanding Prosperity Impact Collaborative (EPIC) Consumer Debt Primer.
1. Who has consumer debt? Almost everyone.
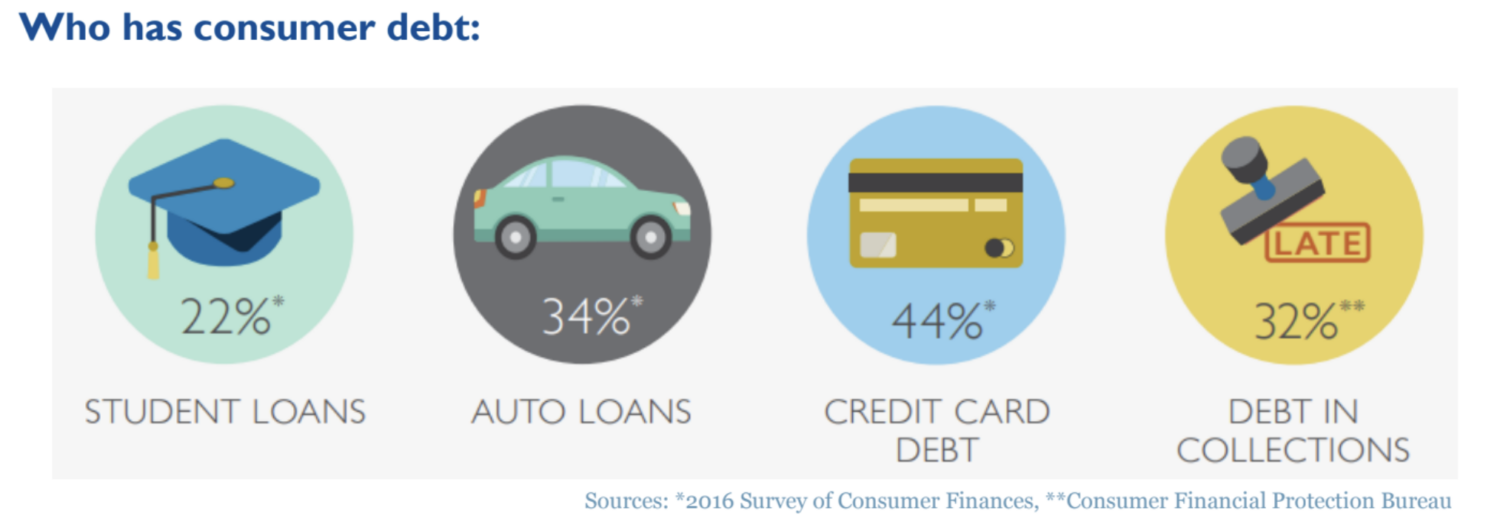
Debt is a nearly universal aspect of American life: 98 million U.S. households (78 percent) have some form of debt, including mortgages. The majority are managing it without problems, but those who struggle face serious consequences that strain their finances, prevent wealth-building, and harm their health and wellbeing.
2. Although total mortgage debt remains below 2008 levels, non-mortgage debts are up $1.5 trillion.
Aggregate Outstanding Household Debt (Trillions of Dollars)

Aggregate Consumer Debt by Type (Trillions of Dollars)

Data Source: Federal Reserve Bank of New York, Household Debt and Credit Report, 2017Q3
Most new debt is from student loans and auto loans. Neither directly helps build wealth, though they are often essential for people’s livelihoods. Both types of debt have high and rising default rates signaling that, for many borrowers, these debts are not delivering the expected benefits.
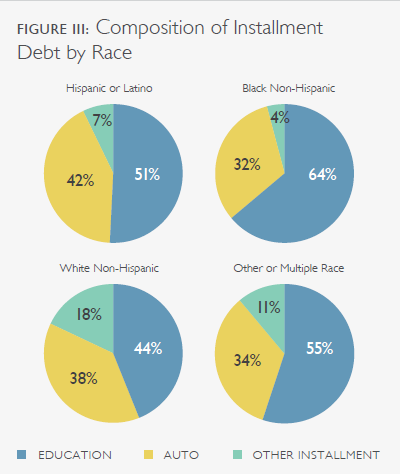
3. The racial wealth gap was enormous before the Great Recession. Since then, student loans have made it worse.
Composition of Installment Debt by Race
Median Family Wealth by Race/Ethnicity, 2001-2016

Data source: Urban Institute calculations from Survey of Financial Characteristics of Consumers 2001-2016
Home equity is the largest component of the racial wealth gap, but consumer debt also contributes. Student debt has significantly increased the racial wealth gap, as people of color tend to borrow more to attend college and many face wage discrimination at work. People of color generally hold a greater proportion of unsecured debt, which has the greatest likelihood of leading to financial insecurity.
4. Low-income households have the highest debt burden, most of which is unsecured student loans.
Debt burdens and the distribution of installment debts by percentile of income


While the median debt among low-income households is lower than for wealthier households, paying down debt is a greater challenge. These households have more debt per dollar of income and fewer assets than higher-earning households. Student loans contribute greatly to this imbalance.
5. About five percent of all debt is delinquent. Regardless of income level, most people with collections listed on their credit report have medical debt.
Proportion of consumers with debt in collections with medical, telecom, and utilities tradelines

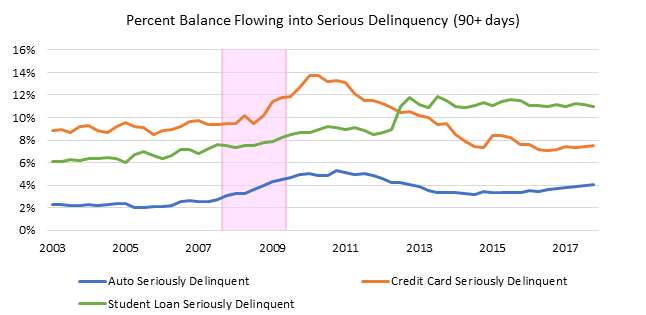
Percent of Balances 90+ Days Delinquent
Data Source: Federal Reserve Bank of New York, Household Debt and Credit Report, 2017Q3
Credit card default rates are relatively healthy, but student loan defaults have been above 10 percent since 2012 and auto loan defaults are double the pre-Recession rate. Medical debt is the most common type of debt in collections listed on credit reports. Medical debt in collections is nearly as common among high-income families as it is among low-income families. Yet low-income households frequently struggle with debts for basic services like electricity and internet service.
Learn more about the changing dynamics of consumer debt, how households are managing the debt they are carrying, and the conditions under which it is a source of financial insecurity versus an opportunity for future mobility in the Consumer Debt Primer.
A Financial Security Threat in the Courtroom
Medical Debt and its Impacts on Health and Wealth: What Can Philanthropy Do to Help?
Majoring in Debt: Why Student Loan Debt is Growing the Racial Wealth Gap and How Philanthropy Can Help
Set Up to Fail: Fines, Fees & Financial Insecurity
Strong Foundations: Housing Security Solutions Framework
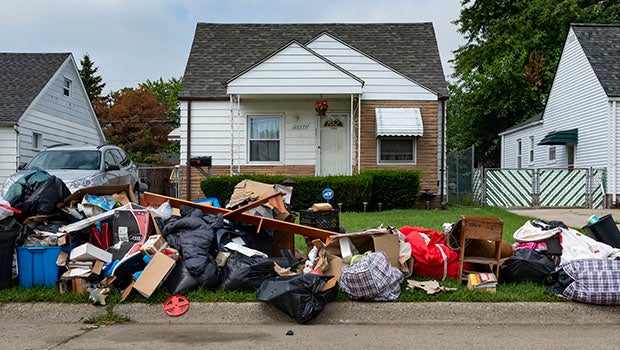
The COVID-19 Eviction Crisis: an Estimated 30-40 Million People in America Are at Risk
The True Cost of Caregiving
Strong Foundations: Financial Security Starts with Affordable, Stable Housing