More Choices, More Questions: Is the Financial Marketplace Truly Delivering Resilience?
Erin Borġ (Thiemann)
Associate Director, Inclusive Financial System
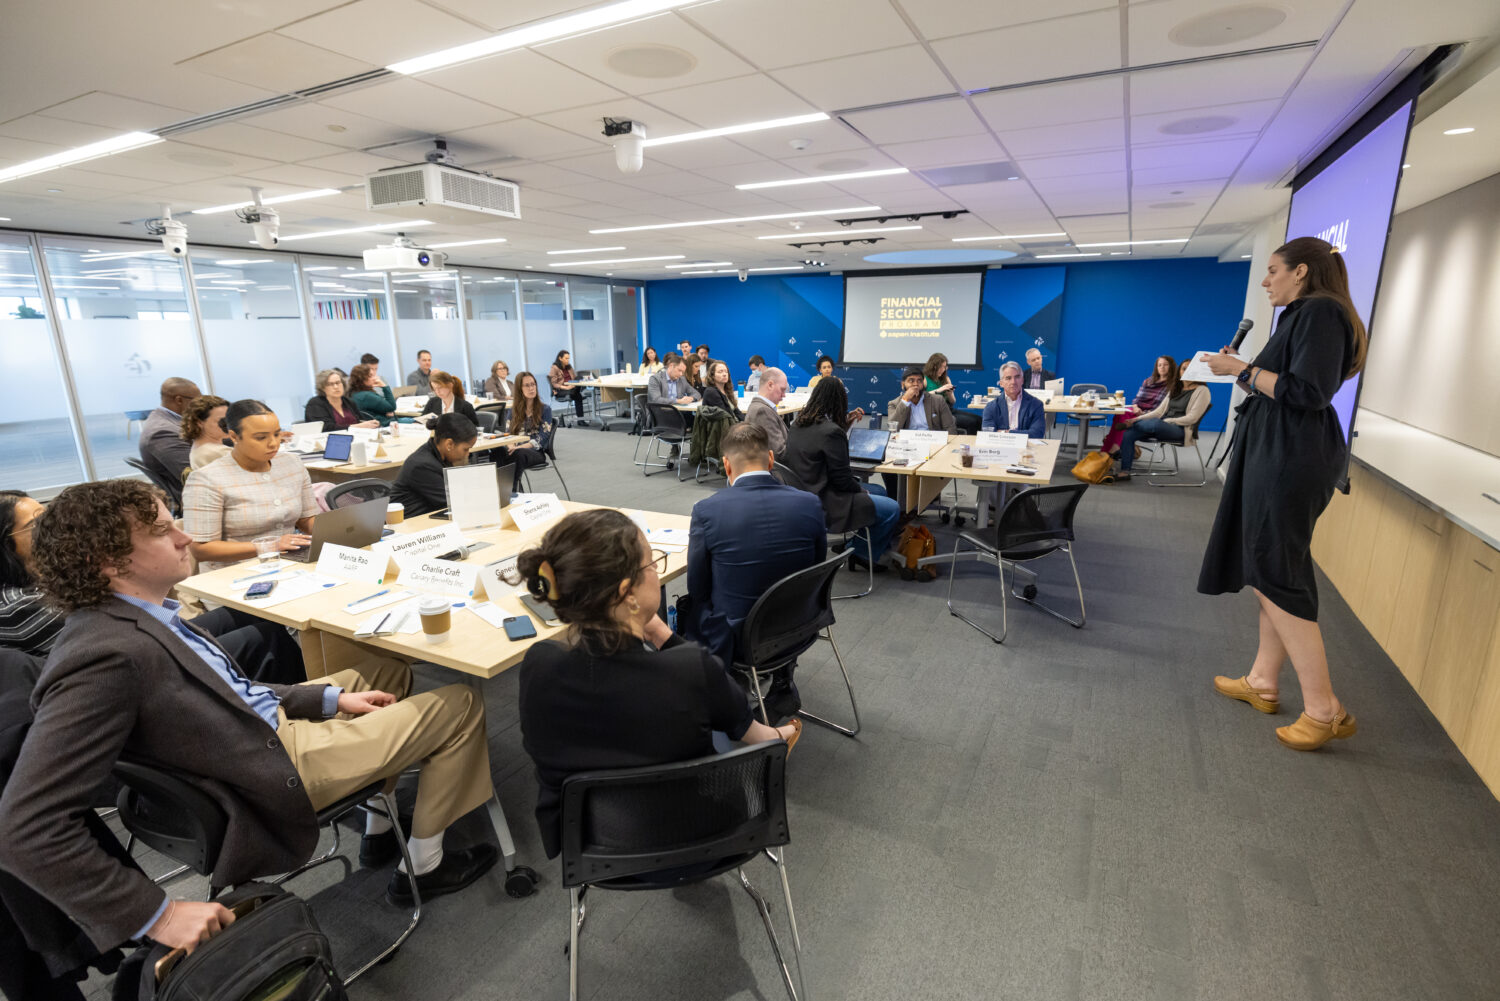
On April 22, the Aspen Institute Financial Security Program (Aspen FSP) hosted a gathering on financial shocks, a topic that feels both urgent and familiar. Held under Chatham House Rule, this Financial Shocks Refinery was designed to update our understanding of the full picture of expense shocks—both how people are navigating unexpected expenses, and also what products and tools people use to recover from them.
To tackle this topic, we welcomed both long-time collaborators and brilliant new faces, all possessing unique insights into how individuals and families navigate the unexpected. We brought together researchers who see the macro-trends of expense shocks, the supply-side providers who see the granular, real-time transaction data of how people are addressing shocks, and the community practitioners who see the intersection of the trends and transactions in the lived experience of the people they serve every day.
Covering the latest research on shocks and the landscape of marketplace solutions, our conversations explored the relationship between financial resilience and wealth building, asking “How is our financial system delivering on financial resilience for households when they inevitably face an unexpected expense?”
The Through-Line: Why Shocks Matter for Wealth
At Aspen FSP, household wealth is our north star. But wealth isn’t built in a vacuum. It requires financial resilience, which we define as the ability to withstand a shock without interrupting basic needs or being pulled off track from long-term goals.
As we grounded our day in the data, a sobering reality emerged: If more households had the cash flow and savings buffers to absorb these hits, we wouldn’t need to focus so heavily on private sector product solutions. But today, households often don’t have the resources to manage unexpected expenses, especially if those expenses happen in quick succession (like your car breaking down the same month you have an unexpected trip to urgent care). With impending changes to the labor market in the coming years, we expect that liquidity solutions will become even more important. Families need liquidity solutions that they can access quickly and affordably in order to get back on track building wealth.
If more households had the cash flow and savings buffers to absorb these hits, we wouldn’t need to focus so heavily on private sector product solutions.
Shocks Aren’t New, But the Solution Set Has Expanded
Expense shocks are not a new challenge for family finances. Since there have been cars, there have been car breakdowns and mechanics who need to be paid. During the event, someone asked the room a pointed question: “What is actually new here?”
The answer was clear. The “demand side” of shocks—the type, frequency, and severity—isn’t radically different than it was five or even ten years ago. Expense shocks are common: Most families experience multiple expense shocks each year, and their costs can quickly add up. People are still primarily grappling with medical bills, car repairs, home maintenance, and the unexpected costs of caring for a child or parent. While these shocks are getting more expensive, the median shock sizes haven’t shifted drastically in ten years.
What is new is the size of the solutions marketplace. For decades, consumer advocates have asked for more solutions to meet liquidity needs quickly and affordably. The market delivered robustly. From emergency savings products, to advances in credit underwriting (cash flow and LLM-driven models), to entirely new categories like Buy Now, Pay Later (BNPL), the options have exploded.
Mission Accomplished? Not Quite.
With so many new tools, do we get to hang a “Mission Accomplished” banner? The consensus in the room was a resounding not yet.
The data show that consumers are saying “yes” to these new entrants in the liquidity market, like BNPL and Earned Wage Access. But are these products fully addressing shocks, or are households cobbling together multiple solutions just to make it to the next paycheck and dealing with the aftermath (fees, interest, or smaller paychecks) later? Overall, are households better off for the financial products that are now available in the market? What evidence would tell us if this expanded set of choices is delivering more ladders and fewer chutes?
This is where the picture gets messy. Households’ financial lives are fragmented and growing more so each year. A person may look like they are completely underwater according to one set of account data, but they may have accounts at three other institutions that tell a different story. We don’t yet have a data set that shows us the complete financial life of a household (a perfect use case for open banking, if I may say so!). So we are left with a series of critical, empirical questions:
- For whom is this expanded toolkit delivering financial resilience?
- For whom is it simply facilitating creative product stacking—combining savings, loans from family or friends, plus a formal credit product? Are some solution sets working better than others?
- For whom is this expanded toolkit a navigation challenge rather than an access challenge?
Key Themes Demonstrate We Have More Work Ahead
During our breakout sessions on specific shock categories—car repair, phone replacement, roof repair, and pet care—a few key themes surfaced:
- Moving toward more nuanced indicators: We have a richer set of financial security indicators to pull from beyond traditional solvency measures, including indicators like “zero balance days” or “stress days”—the number of days at the end of a pay cycle with zero purchases. A better understanding of when households might be vulnerable before an account goes negative creates an opportunity for providers to offer liquidity solutions before an insufficient balance fee hits.
- Avoiding the urgency trap: For a gig worker, a car breakdown can become an income shock in addition to an expense shock. This extreme urgency creates a high stress environment where finding a solution quickly often outweighs long-term higher financial impacts.
- Learning from the “after-shock impact”: How does the experience of an expense shock change future consumer behavior when they experience it again? For example, when someone breaks their phone and needs to buy a new one, how does prior experience change their choices? Do they opt to buy insurance or choose not to finance it in store now that they know the costs associated with their last phone?
- Young adults breaking the mold: Some young adults are priced out of, or less interested in, owning key assets that drive some of the largest shocks, such as houses and cars. How does this shift in ownership trends change the expense shocks they face most often, e.g. fewer car repairs? What other financial impacts emerge as a result of that shift, e.g. less asset ownership relative to older cohorts?
- Cautious optimism (for once) about AI: Figuring out the optimal solution based on the expense shock and a household’s unique financial situation is even more challenging now that there are more choices. Is it better to put this HVAC repair on a credit card, a HELOC, or borrow from retirement savings? The answer is often “it depends.” Getting personalized advice with their financial goals in mind has historically been out of reach for most people. There was cautious optimism in the room about the potential for AI to provide personalized financial advice—sometimes alongside a coach or navigator—offering a solution that has not previously been possible or cost-effective.
Looking Ahead: Walking and Chewing Gum
If we want to build wealth in this country, we have to be able to walk and chew gum at the same time: supporting the innovation of liquidity products while ensuring they don’t become a sophisticated mask for deeper systemic fragility. We need products designed for the “planner,” who can make use of a range of solutions to manage cash flow and effectively stack products to minimize costs and spread out expenses; the “juggler”, who has to cobble together products that may end up costing more in the long run; and everyone in between. And perhaps just as importantly, we need to be able to distinguish between these users in our data.
A heartfelt thank you to our partners at Wells Fargo for making this Refinery possible. To everyone who rolled up their sleeves with us: Your curiosity is exactly what we need to turn these insights into a financial system that actually works for everyone.
Widespread and Costly: Expense Shocks Challenge Family Finances and Interrupt Wealth Building
Moving from Consensus to Consequence in Global Fraud and Scam Prevention
The White House Acts on Scams: What Comes Next
Why Current Solutions Fail Our Most Painful Financial Shocks: Insights from our Community Advisory Group
A Persistent Challenge: How Financial Shocks Continue to Undermine Family Financial Security
Five Forces of Change Shaping the Next Decade of Inclusive Finance
Surviving the Storms: How Severe Weather Hazards Challenge the Financial Security of Small Businesses
How the National Strategy for Financial Inclusion Can Help Households Build Wealth